


Senior Equity Analyst
Equity research CDON Q3 2026: Strong GMV momentum and Fyndiq relief
23 Okt 2026
Read the full report here:
GMV grew 18% in the Q3 2026, ahead of expectations, with growth accelerating over the quarter. Fyndiq grew GMV 11% despite new EU duties on low-value parcels. Adjusted for one-off costs, EBITDA was broadly in line with our forecasts. We raise our base case fair value.
GMV momentum surprisingly strong
Gross Merchandise Value (GMV) grew in the double digits (+18%), once again stronger than expected, and at a +5 p.p. accelerated pace vs the previous quarter. The company says operating momentum improved rapidly in September with 32% group GMV growth following the launch of a new product-data service to improve visibility on Google Shopping. Also, sales from large European merchants continued to grow. Fyndiq GMV was up 11 per cent, better than feared, despite new EU duties on low-value parcel imports. Retail media advertising has not yet generated any revenue, which the CEO labels as a disappointment. Nevertheless, the strong GMV momentum seems to persist into Q4 2026, driven by increased supply, the improvements in product feed mentioned, and some share gains from international discount platforms. Moreover, highly anticipated gaming launches during Q4, including GTA VI, should help underpin GMV growth in the important Home electronics category. It is early days, but Fyndiq also appears more resilient than expected to the EU’s abolition of the de minimis exception to import duties. Both GMV (+11%) and take rate (-0.1 p.p.) held up better than we had feared in the third quarter, and underlying EBITDA improved somewhat. In November, the EU will impose an additional EUR 2 duty on small parcels. While this creates some uncertainty short-term, the recent quarter suggests that Fyndiq can navigate choppy trade policy waters better than many discount peers.
Early evidence of coveted positive “Flywheel”/network effect
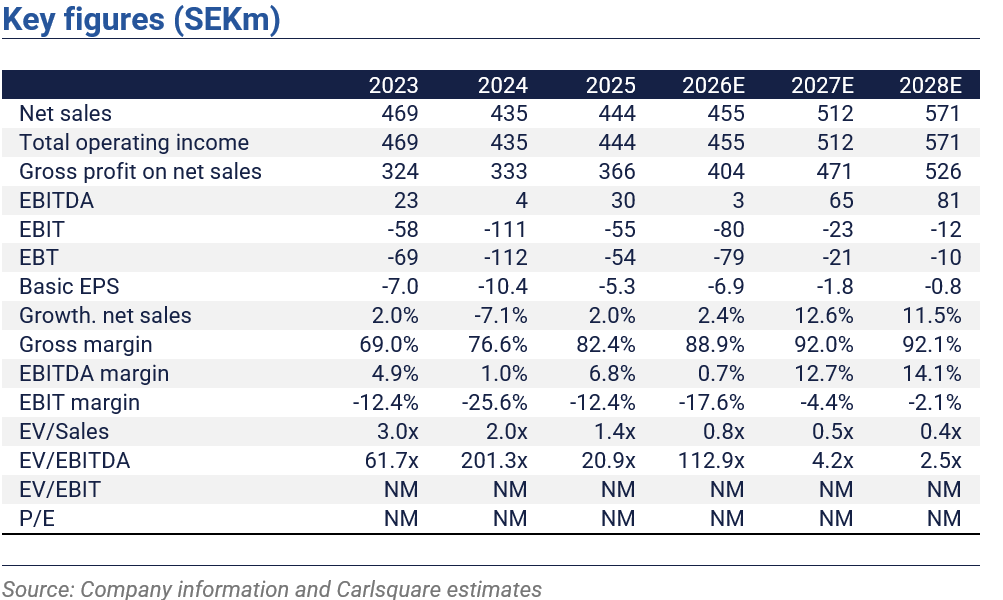
Reported EBITDA for the group decreased to SEK-5.4m (12), compared to our forecast of SEK 3m. However, adjusted for 1P closure costs (SEK -6.4m) and a one-off AI incident cost (SEK -2m), they were largely in line with our expectations despite lower margins. Management says its ambition for 2027 is unchanged, with EBITDA approaching SEK 100m, and expects operating leverage to appear toward year-end as GPAM grows with a largely fixed cost base. We view the Q3 earnings as a positive indication that the growth initiatives are bolstering sales increases. Also, Fyndiq’s performance supports our view that the segment is less affected by the EU de minimis reform than larger international discount peers (admittedly, our sources on the latter are, so far, mostly media reports). All in all, we only make minor adjustments to our estimates.
Outlook and Fyndiq relief support a higher valuation
Combining a DCF valuation with a multiple valuation, we adjust the fair value to some SEK 86 (83) per share in a base case scenario. The increase is due to somewhat higher growth and earnings estimates for 2027-2028E as well as slightly higher peer valuation multiples at EV/EBITDA NTM of ~12x. The fact that Fyndiq growth and take rate has held up better than feared is a relief in our view and should help underpin investor sentiment.
Disclaimer
Carlsquare AB. www.carlsquare.se, hereafter referred to as Carlsquare, conducts operations in Corporate Finance and Equity Research and thereby publishes information about companies, including analyses. The information has been compiled from sources that Carlsquare considers reliable. However, Carlsquare cannot guarantee the accuracy of the information. Nothing written in the analysis should be regarded as a recommendation or invitation to invest in any financial instrument, option or similar. Opinions and conclusions expressed in the analysis are intended solely for the recipient.
The content may not be copied, reproduced, or distributed to any other person without the written consent of Carlsquare. Carlsquare shall not be liable for any direct or indirect damage caused by decisions made based on information contained in this analysis. Investments in financial instruments provide opportunities for capital appreciation and profits. All such investments are also associated with risks. The risks vary between different types of financial instruments and combinations thereof. Historical returns should not be considered as an indication of future returns.
The research is not directed at U.S. Persons (as that term is defined in Regulation S of the United States Securities Act and interpreted in the United States Investment Companies Act 1940) and may not be distributed to such persons. Nor is the analysis aimed at such natural or legal persons where the distribution of the analysis to such persons would involve or entail a risk of violation of Swedish or foreign law or regulations.
The analysis is a so-called commissioned analysis where the analysed company has signed an agreement with Carlsquare for analysis coverage. The analyses are published continuously during the contract period and against customary fixed remuneration.
Carlsquare may or may not have a financial interest in the subject of this analysis. Carlsquare values ensuring objectivity and independence and has therefore established procedures for managing conflicts of interest.
The analysts do not and may not own shares in the analysed company.

Ähnliche News


